Semiconductor Market Growth: How AI, IoT & Advanced Electronics Are Reshaping Demand
Semiconductor Market Size
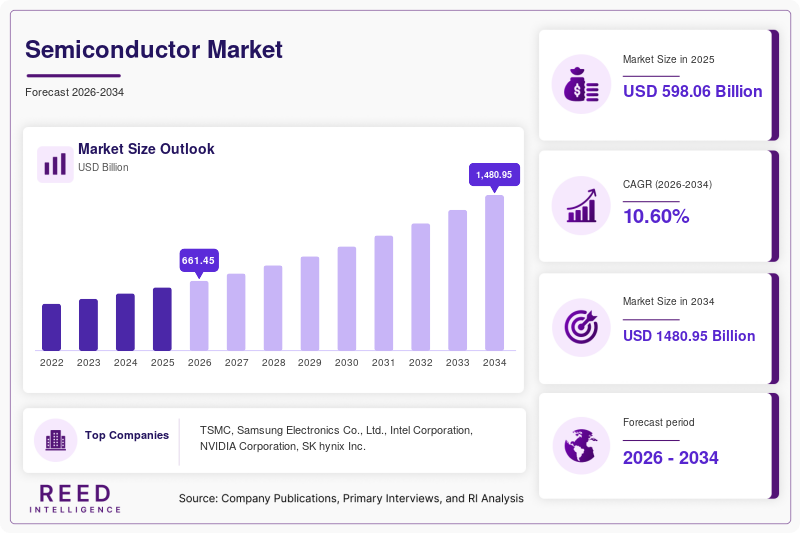
The global Semiconductor Market was valued at USD 598.06 billion in 2025 and is projected to grow from USD 659.66 billion in 2026 to USD 1,480.95 billion by 2034, registering a CAGR of 10.60% during the forecast period from 2026 to 2034.
Semiconductors are fundamental components in computing, telecommunications, automobiles, consumer electronics, industrial equipment, aerospace systems, data centers, medical devices, and increasingly AI-enabled products. The industry encompasses memory, logic, microprocessors, analog devices, discrete components, sensors, optoelectronics, and other integrated circuits.
The semiconductor industry is experiencing strong demand from data-center infrastructure and artificial intelligence. WSTS's August 2026 update showed Memory growth of 305% year over year in the first half of 2026 and Logic growth of 45%, reflecting the scale of investment in accelerated computing and AI infrastructure.
Key Takeaways
-
Market size: The global Semiconductor Market is projected to reach USD 1,480.95 billion by 2034.
-
CAGR: The market is projected to grow at 10.60% from 2026 to 2034.
-
Dominant component: Memory accounted for approximately 30% share.
-
Fastest-growing component: Logic is projected to grow at approximately 12.8% CAGR.
-
Dominant application: Consumer Electronics represented approximately 28% share.
-
Fastest-growing application: Data Centers & AI is projected to grow at approximately 18.6% CAGR.
-
Dominant region: North America accounted for approximately 30% share.
-
Fastest-growing region: Asia Pacific is projected to grow at approximately 12.4% CAGR.
Request a Sample: https://reedintelligence.com/market-analysis/semiconductor-market/request-sample
Semiconductor Market Trends
Artificial Intelligence and Accelerated Computing
Artificial intelligence is reshaping semiconductor demand by increasing requirements for computing capacity, memory bandwidth, networking performance, and high-speed storage.
AI accelerators require high-performance logic alongside high-bandwidth memory and advanced packaging. This is increasing semiconductor content across data-center systems and creating demand for GPUs, AI accelerators, CPUs, HBM, networking processors, and specialized computing components.
WSTS identified AI infrastructure, HBM, and accelerated computing platforms as major contributors to semiconductor industry expansion. Its June 2026 forecast projected the global semiconductor market to exceed USD 1.5 trillion, with Memory forecast to surpass USD 800 billion during the year.
Advanced Packaging and Heterogeneous Integration
Advanced packaging is becoming increasingly important as semiconductor performance requirements rise. Instead of relying exclusively on larger monolithic chips, manufacturers are combining multiple dies within advanced packages.
Technologies such as chiplets, 3D integration, and high-bandwidth interconnects are supporting higher performance while allowing different semiconductor components to be integrated within a single package.
Intel's advanced-packaging portfolio includes Foveros, EMIB, and EMIB-T technologies designed to connect multiple semiconductor dies within high-performance packages.
Increasing Semiconductor Content in Vehicles
Modern vehicles are incorporating semiconductors across advanced driver-assistance systems, infotainment, connectivity, power management, battery management, electrification, and automated driving.
Electrification increases semiconductor requirements for power conversion, motor control, battery systems, charging infrastructure, and thermal management. Software-defined vehicle architectures are also increasing demand for high-performance processors and automotive networking components.
This trend is creating demand across analog, power, microcontroller, sensor, memory, and logic semiconductor categories.
Expansion of Data-Center Infrastructure
Cloud computing and AI infrastructure require processors, memory, networking chips, storage controllers, power-management semiconductors, optical components, and specialized accelerators.
The expansion of data centers is therefore creating demand across multiple semiconductor product categories. Energy efficiency is also becoming increasingly important as operators seek improvements in transistor performance, packaging density, memory bandwidth, and power consumption.
Semiconductor Market Drivers
Artificial Intelligence Infrastructure Expansion
AI workloads require substantially greater computing capacity and memory bandwidth than many conventional computing applications. GPUs and AI accelerators depend on advanced logic, HBM, and sophisticated packaging technologies.
WSTS's 2026 industry data indicates that Memory and Logic are among the strongest growth categories, reflecting increasing semiconductor demand from AI infrastructure and accelerated computing.
This demand affects multiple layers of the semiconductor supply chain. Logic manufacturers benefit from accelerator demand, memory producers benefit from HBM requirements, foundries benefit from leading-edge wafer demand, and packaging suppliers benefit from increasingly complex multi-die architectures.
Growth of Automotive Electronics
The increasing use of electronics in vehicles is expanding semiconductor requirements. Automotive manufacturers are integrating advanced computing, connectivity, sensors, electrification technologies, and automated-driving capabilities into vehicle platforms.
Electric vehicles require semiconductors for battery management, power conversion, motor control, charging, and thermal-management systems. At the same time, ADAS and software-defined vehicles require processors, sensors, memory, networking, and communication components.
Data-Center and Cloud Investment
Data-center infrastructure is becoming an important source of semiconductor demand. Cloud platforms and AI systems require high-performance processors, accelerators, memory, networking components, storage, optical connectivity, and power-management devices.
The increasing computational requirements of AI workloads are further raising semiconductor content per data-center system and supporting demand for advanced logic, HBM, advanced packaging, and high-speed interconnect technologies.
Semiconductor Market Restraints
High Capital Requirements and Manufacturing Complexity
Leading-edge semiconductor manufacturing requires significant capital expenditure for fabrication plants, lithography systems, process-development equipment, cleanrooms, advanced packaging facilities, and testing infrastructure.
The complexity increases as manufacturers move toward advanced process nodes and three-dimensional architectures. Intel has been developing 18A, 18A-P, and 14A process technologies while expanding advanced-packaging capabilities.
These requirements create substantial barriers to entry. A limited number of companies can economically operate leading-edge fabrication facilities, while many chip designers remain dependent on foundry partners for manufacturing.
Supply-Chain and Geopolitical Exposure
Semiconductor manufacturing relies on globally distributed suppliers of wafers, chemicals, gases, lithography equipment, packaging materials, electronic-design automation tools, and specialized manufacturing equipment.
Export controls and technology restrictions can influence sourcing strategies, manufacturing locations, and investment decisions. Governments are also encouraging domestic semiconductor production to reduce exposure to external supply disruptions.
Regionalization can improve supply resilience but may also increase production costs and create duplication of manufacturing capacity. Semiconductor companies therefore need to balance supply security with global manufacturing economics.
Semiconductor Market Opportunities
Advanced Packaging and Chiplet Architectures
Advanced packaging is becoming a major opportunity as semiconductor manufacturers increasingly combine multiple dies within high-performance packages.
Intel's Foveros, EMIB, and EMIB-T technologies demonstrate the industry's movement toward heterogeneous integration. AI accelerators are further increasing demand for high-bandwidth interconnects, chiplets, substrates, packaging technologies, and advanced testing.
This creates opportunities for semiconductor manufacturers, packaging specialists, substrates suppliers, testing companies, equipment providers, and materials manufacturers.
High-Bandwidth Memory and Custom AI Semiconductors
High-bandwidth memory represents an important growth opportunity because AI accelerators require extremely high memory bandwidth.
Samsung began commercial HBM4 production in February 2026 and subsequently shipped HBM4E samples. The company also announced collaboration with AMD covering HBM4 for AMD Instinct MI455X GPUs and next-generation DDR5 solutions.
The expansion of customer-specific AI accelerators is also creating opportunities for custom memory, chiplets, foundry services, advanced packaging, and application-specific integrated circuits.
Semiconductor Manufacturing Expansion
The expansion of semiconductor manufacturing capacity across different regions is creating opportunities throughout the semiconductor ecosystem.
New fabrication capacity increases demand for semiconductor manufacturing equipment, materials, packaging, testing, cleanroom infrastructure, process technologies, and supply-chain services. Regional manufacturing investments are also supporting the development of domestic semiconductor ecosystems.
Semiconductor Market Segmentation Analysis
By Component
Memory is the dominant component, accounting for approximately 30% share. The segment includes DRAM, NAND, and high-bandwidth memory products used in servers, PCs, smartphones, storage systems, AI accelerators, and other computing equipment.
Logic is projected to be the fastest-growing component, registering an estimated 12.8% CAGR. AI accelerators, high-performance CPUs, GPUs, networking processors, application processors, and custom silicon are increasing demand for advanced logic.
Microprocessors account for approximately 16% share and expand at 9.7% CAGR, while Analog represents approximately 13% and grows at 7.8% CAGR.
Discrete Semiconductors account for approximately 9% share and grow at 6.9% CAGR. Sensors represent approximately 7% share and register an estimated 8.5% CAGR, supported by automotive sensing, industrial automation, and consumer devices.
Optoelectronics account for approximately 6% share and grow at 7.2% CAGR, while Others account for approximately 19% share and grow at 7.0% CAGR.
By Application
Consumer Electronics is the dominant application, accounting for approximately 28% share. Smartphones, computers, televisions, wearables, gaming equipment, home appliances, and other connected devices contain semiconductor components across processing, memory, connectivity, power management, sensing, and display functions.
Data Centers & AI is projected to be the fastest-growing application, registering an estimated 18.6% CAGR. AI accelerators, server processors, HBM, networking components, optical devices, and high-performance storage are increasing semiconductor content in data-center infrastructure.
Communication applications account for approximately 18% share and grow at 9.3% CAGR, supported by 5G infrastructure, networking equipment, and high-speed connectivity.
Automotive represents approximately 16% share and grows at 11.7% CAGR, driven by electrification, ADAS, vehicle connectivity, and increasing computing requirements.
Industrial applications account for approximately 13% share and grow at 8.4% CAGR, while Aerospace & Defense represents approximately 6% share and grows at 9.6% CAGR. Others account for approximately 19% share and grow at 7.2% CAGR.
Semiconductor Market Regional Analysis
North America
North America is the dominant regional market, accounting for approximately 30% share. The region benefits from major semiconductor designers, cloud-computing companies, AI accelerator developers, equipment suppliers, research institutions, and expanding domestic fabrication investments.
The United States is also strengthening domestic semiconductor manufacturing. Intel's RAMP-C program supported development of domestic leading-edge CMOS technology and manufacturing, while Intel continues to expand its advanced process and packaging roadmap.
North American semiconductor demand is strongly connected to AI infrastructure, cloud computing, data centers, communications equipment, defense electronics, automotive systems, and advanced computing.
North America is projected to grow at approximately 9.5% CAGR during 2026–2034.
Europe
Europe is projected to grow at approximately 8.1% CAGR during 2026–2034. Automotive semiconductors, industrial electronics, power devices, sensors, communications, and specialized embedded systems represent important demand areas.
The European semiconductor ecosystem is also supported by investments in manufacturing capacity and technology development. Automotive and industrial applications provide a diversified demand base beyond the AI-driven data-center cycle.
Asia Pacific
Asia Pacific is projected to be the fastest-growing region, with approximately 12.4% CAGR.
The region combines semiconductor manufacturing, electronics assembly, consumer-device production, memory manufacturing, foundry operations, automotive electronics, and expanding data-center infrastructure.
Taiwan remains a critical advanced-manufacturing center. TSMC's manufacturing network exceeded 17 million 12-inch-equivalent wafers of annual capacity in 2025, while its Arizona expansion includes additional fabs and advanced packaging.
South Korea is another major semiconductor center, particularly for memory and advanced semiconductor technologies. Samsung's HBM4 and HBM4E developments demonstrate the region's growing role in AI-memory supply.
Latin America
Latin America is projected to grow at approximately 9.0% CAGR. Semiconductor consumption is supported by automotive manufacturing, telecommunications, industrial electronics, consumer devices, energy infrastructure, and connected-device deployment.
The region remains more dependent on imported semiconductor components than the principal manufacturing hubs. Changes in global pricing, logistics, currency conditions, and supply availability can therefore influence local procurement patterns.
Middle East & Africa
The Middle East & Africa region is projected to grow at approximately 10.2% CAGR.
Demand is associated with telecommunications infrastructure, data centers, industrial automation, energy systems, defense electronics, smart-city infrastructure, and consumer electronics.
The expansion of cloud and AI infrastructure creates additional semiconductor demand through servers, networking equipment, storage systems, power-management systems, and optical connectivity.
Semiconductor Market Competitive Landscape
The Semiconductor Market includes integrated device manufacturers, fabless chip designers, foundries, memory manufacturers, semiconductor equipment companies, and specialized semiconductor suppliers.
Competition increasingly depends on process technology, manufacturing capacity, chip-design capabilities, energy efficiency, advanced packaging, intellectual property, customer relationships, and supply reliability.
TSMC remains a major foundry participant, operating advanced manufacturing facilities across Taiwan and overseas. Its manufacturing capacity and expansion into advanced packaging allow it to serve high-performance computing, smartphone, automotive, and AI customers.
Samsung Electronics competes across memory, logic, foundry, and advanced packaging. Its HBM4 production and HBM4E development demonstrate the integration of memory technology with AI-computing requirements. The company is also pursuing substantial long-term semiconductor investment in Korea, including HBM manufacturing infrastructure.
Key Market Players
-
TSMC
-
Samsung Electronics Co., Ltd.
-
Intel Corporation
-
NVIDIA Corporation
-
SK hynix Inc.
-
Micron Technology, Inc.
-
Broadcom Inc.
-
Qualcomm Incorporated
-
Advanced Micro Devices, Inc.
-
Texas Instruments Incorporated
-
MediaTek Inc.
-
Infineon Technologies AG
-
STMicroelectronics
-
NXP Semiconductors N.V.
-
Renesas Electronics Corporation
Recent Developments in the Semiconductor Market
September 2026 – Intel Corporation
Intel Foundry and ASML reported continued progress in High Numerical Aperture EUV technology, with more than 1 million wafers processed across tool certification, R&D, and volume-production activities, including selected layers for Panther Lake processors.
September 2026 – Samsung Electronics
Samsung announced expanded semiconductor collaborations, including a strategic partnership with Mistral AI for intelligence-driven semiconductor infrastructure and an expanded collaboration with ASML for next-generation semiconductor manufacturing.
Semiconductor Market Segments
By Component
-
Memory
-
Logic
-
Microprocessors
-
Analog
-
Discrete Semiconductors
-
Sensors
-
Optoelectronics
-
Others
By Application
-
Consumer Electronics
-
Communication
-
Automotive
-
Industrial
-
Data Centers & AI
-
Aerospace & Defense
-
Others
By Region
-
North America
-
Europe
-
Asia Pacific
-
Middle East & Africa
-
Latin America
Frequently Asked Questions
What is the size of the Semiconductor Market in 2026?
The global Semiconductor Market is valued at USD 659.66 billion in 2026.
What will the Semiconductor Market size be by 2034?
The global Semiconductor Market is projected to reach USD 1,480.95 billion by 2034, registering a CAGR of 10.60% during 2026–2034.
Which component dominates the Semiconductor Market?
Memory is the dominant component, accounting for approximately 30% share.
Which semiconductor component is growing fastest?
Logic is projected to be the fastest-growing component, registering approximately 12.8% CAGR.
Which application is growing fastest in the Semiconductor Market?
Data Centers & AI is projected to be the fastest-growing application, with an estimated CAGR of 18.6%.
Which region is expected to grow fastest in the Semiconductor Market?
Asia Pacific is projected to be the fastest-growing region, with approximately 12.4% CAGR during 2026–2034.
What is driving growth in the Semiconductor Market?
Artificial intelligence, accelerated computing, data-center expansion, automotive electrification, advanced driver-assistance systems, connected devices, and increasing semiconductor content across industrial and consumer applications are major factors supporting market growth.
What are the major opportunities in the Semiconductor Market?
Advanced packaging, chiplet architectures, high-bandwidth memory, custom AI semiconductors, semiconductor manufacturing expansion, and specialized semiconductor technologies represent major opportunities across the industry.
Conclusion
The global Semiconductor Market is projected to grow from USD 659.66 billion in 2026 to USD 1,480.95 billion by 2034, registering a CAGR of 10.60% during the forecast period.
Artificial intelligence, accelerated computing, data-center expansion, automotive electrification, increasing semiconductor content in vehicles, and advanced electronics are supporting demand across the semiconductor ecosystem.
Memory remains the dominant component, while Logic is projected to record the fastest component growth. Consumer Electronics represents the largest application, while Data Centers & AI is projected to expand at the fastest rate. North America remains the largest regional market, while Asia Pacific is projected to record the fastest regional growth.
Advanced packaging, chiplet architectures, HBM, custom AI semiconductors, and manufacturing capacity expansion are creating opportunities across chip design, foundries, memory, packaging, equipment, materials, and testing.
The semiconductor industry is consequently evolving toward increasingly integrated computing architectures in which processing performance, memory bandwidth, advanced packaging, energy efficiency, and manufacturing capacity collectively determine system-level performance.
Full Report: https://reedintelligence.com/market-analysis/semiconductor-market

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Indonesia